SPY -1.05%
BND -0.24%
QQQ -1.18%
DIA -1.59%
VNQ -1.16%
GLD -1.82%
BTC -2.41%
AAPL +1.37%
GOOGL +2.46%
NVDA -2.64%
MSFT -0.98%
META +4.36%
AMZN -2.93%
TSLA -2.29%
UBER -2.54%
GS -8.50%
BAC -8.54%
JPM -2.49%
BRK.A +2.50%
COST -0.82%
XOM -1.44%
BABA -1.72%
WMT +2.01%
SPCX +0.73%
DIS +0.69%
F -4.54%
  • Discounts and special offers
  • Subscriber-only articles and interviews
  • Breaking news and trending topics

Already a subscriber?

By signing up, you accept Moneywise's Terms of Use, Subscription Agreement, and Privacy Policy.

Not interested ?

Retirement
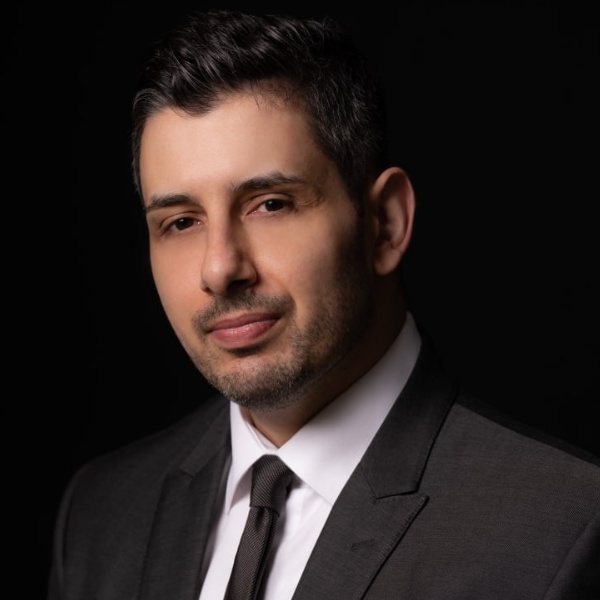
Kevin O’Leary, Barbara Corcoran and Robert Herjavec. Amy Sussman/Getty Images, John Lamparski/Getty Images

Shark Tank’s Kevin O’Leary, Barbara Corcoran and Robert Herjavec all avoid mixing money and family. Why retirees should do the same

When it comes to retirement security, Shark Tank’s Kevin O’Leary, Barbara Corcoran and Robert Herjavec have it made, amassing multiples of the $1.46 million nest egg many Americans believe they need to retire comfortably.

According to The Street, real-estate maven Corcoran, 77, is worth an estimated $100 million. O’Leary, 72, who became a millionaire when he sold his software company Softkey to Mattel for $4.2 billion in 1999, is worth $400 million. Tech security pro Herjavec, 63, is worth north of $300 million.

Advertisement

Notably, none of them have retired, even though they have the money to do so. They keep on investing, building both their wealth and their brands as celebrity millionaires — followed by millions of people of all ages, including older Americans.

Retire on your terms — we'll show you how.

By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.

But all three Sharks have advice that retirees in particular would do well to heed: avoid mixing money and family.

“Money complicates relationships, relationships with your friends, family … so when you don’t have a lot of money, things run smoother,” Corcoran told CNBC Make It.

Here’s what these sharks do to prevent money conflicts with family, and why that’s especially important for retirees who may not have the level of wealth that they’ve achieved.

Sharks don’t loan money to family members

Herjavec made his position on money and family clear in a social post, saying he keeps business and family separate. All his adult children have successful careers, but he hasn’t hired any of them or partnered with them on business ventures.

“I will never lend money to family and I won’t invest with family,” he said. “I will give money to family if they need it and there’s a good reason.”

O’Leary follows the same playbook and applies the strategy with immediate and extended family members who come to him for cash.

“I don’t want to loan anybody money. I don’t want anyone to owe me or to drive a wedge in my family,” he told Business Insider. “So, instead, I’ll agree to a one-time gift.”

He makes it a generous gift and does so happily, not expecting repayment. Then he shakes on it and tells the recipient they are never to talk about the gift — or ask for more money — ever again.

Advertisement

O’Leary feels strongly that handing out loans to loved ones does a disservice to the recipients.

“Something I learned from my mother decades ago is that entitlement is a curse,” he said. “If you guarantee someone that they never have to take risks, they never do.”

Must Read

Why retirees need to be careful giving money to loved ones

Despite the Sharks’ advice, a lot of older Americans are supporting their adult children financially. According to a 2025 AARP survey, 75% of parents are supporting an adult child, shelling out a median contribution of $1,400 a year.

Of those, 42% said it was causing them financial stress. Meanwhile, more than a third of parents who participated in a Pew Research Center survey say financially supporting their adult children is hurting their own finances, USA Today reports. Furthermore, 36% of parents surveyed in January 2025 worry that financially supporting adult children could negatively affect their own retirement plan.

Concerningly, 35% said it was causing them emotional stress, the very kind of strain the sharks warn about when it comes to mixing money and family. Unfortunately, unlike the Sharks, average Americans generally lack the kind of wealth to bestow financial gifts on loved ones.

Advertisement

A 2026 AARP survey found that 56% of adults aged 50 to 64 and 61% of adults aged 65 or more have instead loaned money to family or friends — and they do expect to get paid back. Nate Towers, director at the retirement planning firm Five Pathways Financial, told AARP that’s a risky assumption.

“If you’re going to lend money, you should assume that you might not be repaid,” he said. “If you’re OK with that, then go ahead, but if not, you need to take steps to protect both parties involved.”

Protection means running the numbers (preferably with a financial advisor or tax attorney) to see how such a loan could impact your short-term and long-term security. There are also tax implications of both gifts and loans to family and friends.

A gift of $19,000 or more to a loved one may be subject to a federal gift tax. The IRS sets a minimum interest rate for loans of $10,000 or more to family and friends, and any money you withdraw from an IRA account, a 401(k) or your investment portfolio may also be subject to taxes.

If after crunching the numbers you find that you can’t afford the loan, you may have to be tough as a shark and say no.

You May Also Like

Share this:
Laura Boast Senior Reporter

Laura Boast is a Senior Reporter with Moneywise.com and a lifelong content creator who has reached international audiences at Discovery, CBC, Blue Ant Media, Bond Brand Loyalty and more.

more from Laura Boast

Explore the latest

Disclaimer

The content provided on Moneywise is information to help users become financially literate. It is neither investment, tax nor legal advice, is not intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities, enter into any loan, mortgage or insurance agreements or to adopt any investment strategy. Tax, investment and all other decisions should be made, as appropriate, only with guidance from a qualified professional. We make no representation or warranty of any kind, either express or implied, with respect to the data provided, the timeliness thereof, the results to be obtained by the use thereof or any other matter. Advertisers are not responsible for the content of this site, including any editorials or reviews that may appear on this site. For complete and current information on any advertiser product, please visit their website.

†Terms and Conditions apply.