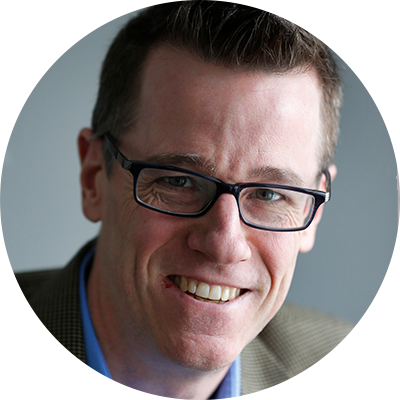
Jamal Robinson didn’t come from money. He started nearly at the bottom, working as a church janitor at 14 before landing a minimum-wage job at Taco Bell, working long shifts while also going to school.
Today, at 40, he’s an American expat living among the glittering skyscrapers of Dubai, in the United Arab Emirates, living comfortably off his $3.5 million nest egg and pulling in $185,000 a year using the 4% percent retirement income rule. His secret? Relentless saving, aggressive investing, and a laser focus on financial freedom.
“I didn’t see a lot of people that were happy with work,” Robinson told CNBC. “In my mind, I always thought that it made the most sense to compress that amount of time in my life. So at 17, I set the goal to retire early at 45, which I wound up hitting six years earlier than expected.”
Thanks for subscribing!
Take control — get our free newsletter.
By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.
Robinson’s journey from minimum-wage worker to multimillionaire retiree is an extraordinary anecdote of the so-called FIRE movement – financial independence, retire early. But it wasn’t luck. It was a ruthless commitment to saving and investing.
How he did it
After high school, Robinson hustled through college, earning a computer engineering degree at Tennessee Tech on a full-ride scholarship while working. He progressed in title and salary through big brands like Amazon, Microsoft, IBM, and Intel. With an MBA, nine certifications and expertise in generative AI, he eventually reached an income of $1.1 million a year.
But instead of chasing the next promotion, he chose financial freedom – and a side goal of shedding his reluctance to spend in ways that reflect his success while maintaining the huge cushion he’s built.
Old habits die hard: As he progressed in the tech industry, Robinson banked huge sums – at one point socking away nearly 90% of his income.
“I still, even to this day, view myself as this minimum wage guy making $5.15 an hour,” Robinson said about his scarcity mindset. “I would make $1 million a year, and I would struggle to spend over $50 on an item.”
That kind of frugality is how in 2024, at just 39, he retired with $3.5 million in savings and investments. He now produces music and DJs in his spare time. He's also writing a book and produces his podcast.
Must Read
- Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
- The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
Strategies to make anyone financially free
Robinson’s hard-earned success may be an outlier, but it’s also a blueprint anyone can follow – if they have ruthless discipline, invest strategically and resist the urge to spend more as they make more.
He successfully avoided lifestyle creep as he amassed his wealth. Every time you get a raise, it’s tempting to upgrade your life, with things like a bigger house, a nicer car or lavish vacations.
But Robinson proved that keeping expenses low and directing extra income into investments can shave decades off your working years. The more you save now, the faster your money can work for you.
Why Dubai?
Dubai isn’t just a playground for the ultra-rich, it’s also a tax haven with no income tax. Robinson, however, still has to pay taxes in the U.S. on his investment withdrawals.
He uses Airbnb to rent apartments for several weeks or months at a time and spends around $4,500 a month this way. He currently resides in a 900-square-foot, two-bedroom apartment right off the beach, for which he's paying a little over $5,000 a month. He allocates around $2,000 a month for food.
“Dubai is actually much cheaper for me than living in most of the major American cities I’ve been in,” he said. “If I spend the same amount of money here, I typically get a much better experience. Or if I spend less money, I can get the equivalent experience.”
He also highlights Dubai's cultural diversity as a reason he chose to stay there. Once his work visa expires in July, he plans to move to some place with more biodiversity where he can feel "feel like I’m more one with nature."
Could you do the same? Absolutely. But it requires intentionality. Retiring early and living abroad takes planning, from securing international health insurance to understanding tax implications.
But for those willing to make the leap, the rewards are undeniable: financial independence, location freedom, and a life on your terms.
You May Also Like
- Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake — here’s what it is and 3 simple steps to fix it ASAP
- A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
Chris Clark is a Kansas City–based freelance journalist covering personal finance, housing and retirement. A former Associated Press editor and reporter, he writes plainspoken stories that help readers make smarter financial decisions.