SPY +1.17%
BND -0.79%
QQQ +2.06%
DIA +0.36%
VNQ +0.15%
GLD -3.47%
BTC -6.00%
AAPL +2.26%
GOOGL +5.02%
NVDA +1.22%
MSFT -4.59%
META -2.09%
AMZN -0.54%
TSLA +5.41%
UBER -1.20%
GS +0.69%
BAC -0.02%
JPM +0.92%
BRK.A +1.14%
COST +2.47%
XOM +3.74%
BABA -9.78%
WMT +0.75%
SPCX -1.98%
DIS -0.35%
F -2.77%
  • Discounts and special offers
  • Subscriber-only articles and interviews
  • Breaking news and trending topics

Already a subscriber?

By signing up, you accept Moneywise's Terms of Use, Subscription Agreement, and Privacy Policy.

Not interested ?

Debt
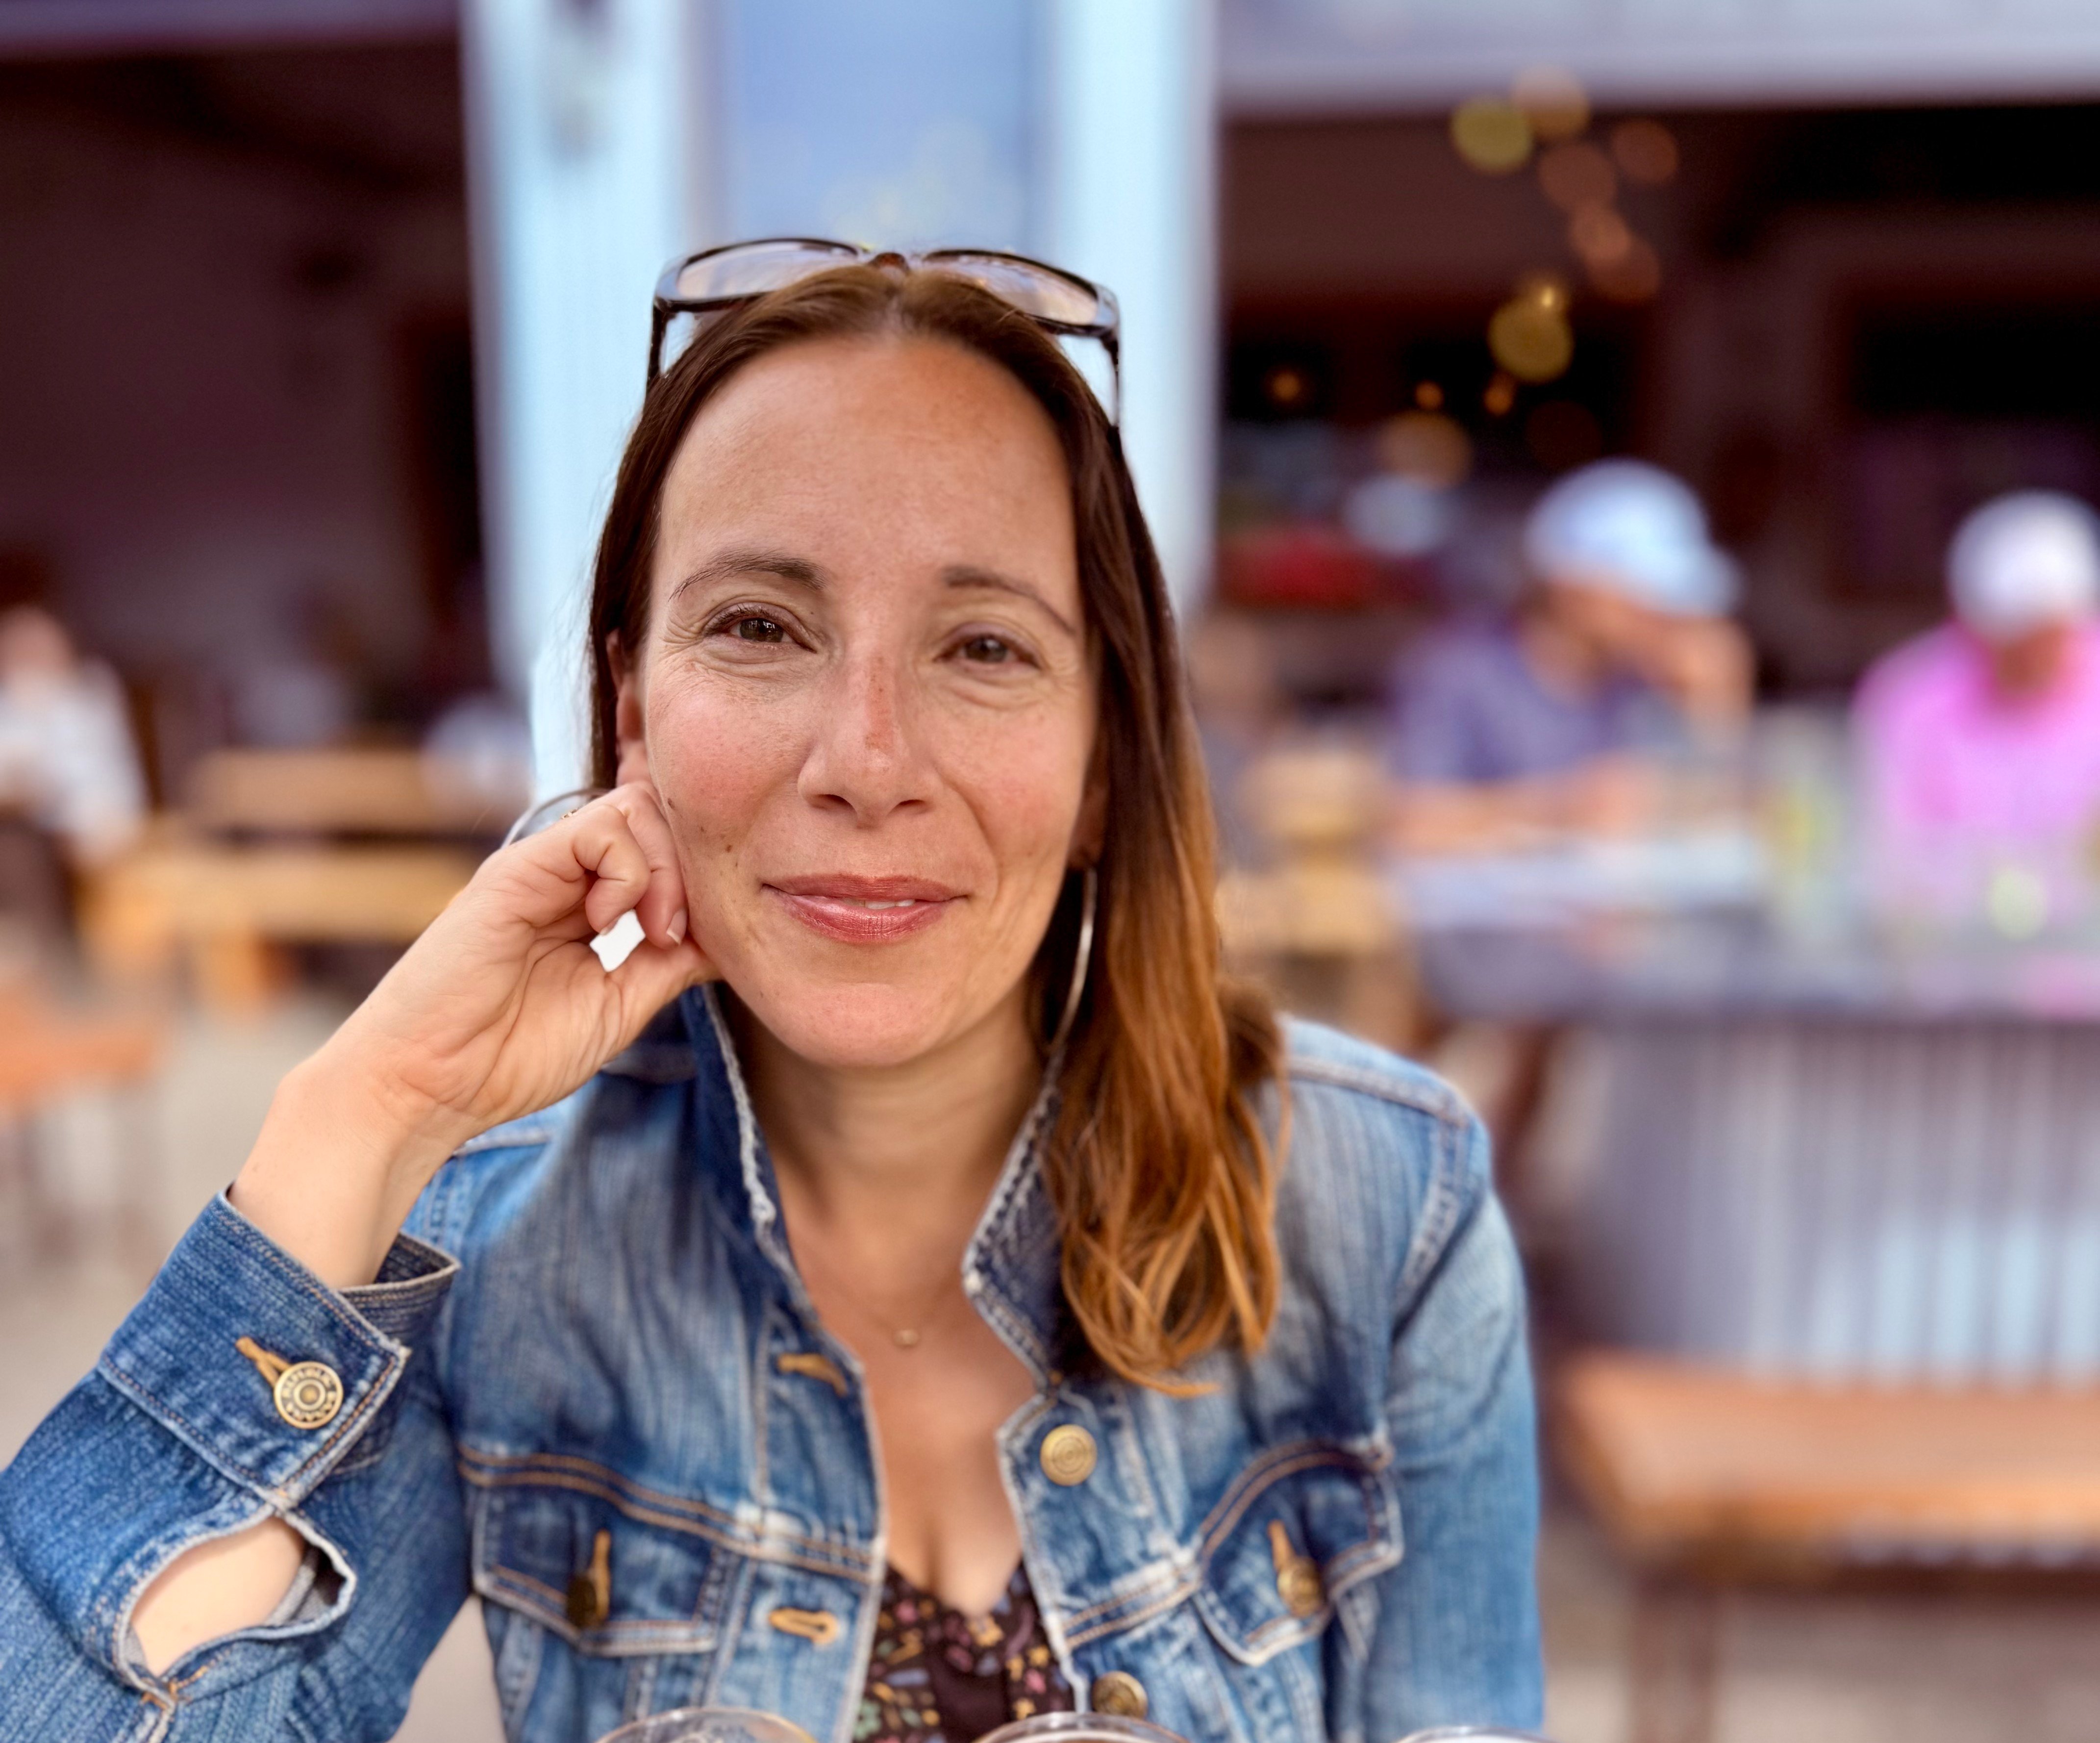
miranda hope miranda__hope/TikTok

‘Mormon Wives’ star Miranda Hope has filed for divorce. But her $12,849 court judgment had nothing to do with her marriage

Miranda Hope is one of the latest “Secret Lives of Mormon Wives” stars to end her marriage. Court records obtained by People show she filed for divorce from Chase McWhorter in September, but the news only surfaced days after castmate Jen Affleck filed for divorce from Zac Affleck on Nov. 3.

The details of how the couple is dividing assets haven’t been made public. But this isn’t the first time Hope’s finances have landed in a Utah courtroom — and the prior case is the one with a lesson anyone can benefit from.

Advertisement

According to Us Weekly, Hope did not respond to a lawsuit filed by Discover Bank in September 2024 over an unpaid credit card balance. As a result, a Utah court entered a default judgment ordering her to pay $12,849.

Take control — get our free newsletter.

By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.

Consumer protection experts warn that ignoring debt collection lawsuits often leads to default judgments, which can allow creditors to pursue wage garnishment, bank account levies or property liens, depending on state law.

Hope’s case is a textbook example of a common but costly mistake. Unlike a divorce, where costs often hinge on two people and a negotiation, this kind of case can turn on a single missed deadline.

A broader trend fueled by technology

When a creditor sues over unpaid credit card debt, the clock starts ticking. If the defendant fails to respond by the court deadline — usually a few weeks — a default judgment can be entered automatically. This appears to have happened in Hope’s case.

According to Pew, debt collection lawsuits in the U.S. have surged back to pre-pandemic levels, reaching over 4.7 million cases per year. Ironically, Utah is “on track to surpass their most recent peak” of debt filings, Pew says.

Research shows that many consumers fail to respond, making default judgments extremely common. Once a judgment is entered, negotiating becomes more difficult and costly.

Hope’s case also reflects a growing trend of aggressive debt collection.

The New York Times reports that creditors are increasingly using AI and automation to identify overdue accounts and file lawsuits at scale, making it faster and cheaper to take consumers to court.

For consumers, this means lawsuits can arrive more quickly, sometimes with little warning — especially when balances are sold to third-party debt buyers.

Advertisement

Must Read

Why this matters

Hope’s legal trouble came as credit card debt continues to climb nationwide. U.S. credit card debt has reached $1.29 trillion, according to CNBC reporting based on Federal Reserve data, driven by inflation and rising interest rates.

Meanwhile, “Mormon Wives” has become a breakout hit, generating widespread social media buzz. This contrast between Hope’s celebrity success alongside ordinary debt problems highlights how common financial stress is and how quickly it can spiral when ignored.

What you should do instead

Hope’s $12,849 judgment isn’t just celebrity gossip — it’s a warning. Credit card debt doesn’t disappear, and lawsuits can move quickly.

If you’re struggling with high debt or tight budgets, here are several key lessons:

Never ignore a lawsuit. Even if you can’t pay, responding preserves your rights and may prevent an automatic judgment.

Advertisement

Communicate early. Creditors may agree to payment plans or settlements before a case escalates.

Consider consolidation. Rolling high-interest balances into a lower-rate debt consolidation loan can reduce monthly payments and prevent accounts from becoming delinquent.

Know when to ask for help. If debt is unmanageable, a bankruptcy attorney or nonprofit credit counselor can clarify your options.

The most important lesson: open the mail, respond on time and seek help before the court gets involved.

With files from Michelle Bates

You May Also Like

Share this:

With a writing and editing career spanning over 15 years, Emma creates and refines content across a broad spectrum of industries, including personal finance, lifestyle, travel, health & wellness, real estate, beauty & fitness and B2B/SaaS/tech.

more from Emma Caplan-Fisher

Explore the latest

Disclaimer

The content provided on Moneywise is information to help users become financially literate. It is neither investment, tax nor legal advice, is not intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities, enter into any loan, mortgage or insurance agreements or to adopt any investment strategy. Tax, investment and all other decisions should be made, as appropriate, only with guidance from a qualified professional. We make no representation or warranty of any kind, either express or implied, with respect to the data provided, the timeliness thereof, the results to be obtained by the use thereof or any other matter. Advertisers are not responsible for the content of this site, including any editorials or reviews that may appear on this site. For complete and current information on any advertiser product, please visit their website.

†Terms and Conditions apply.