SPY +0.38%
BND -0.11%
QQQ +0.57%
DIA -0.30%
VNQ -1.30%
GLD -0.20%
BTC -0.95%
AAPL +2.37%
GOOGL +4.38%
NVDA -0.58%
MSFT +0.22%
META +5.66%
AMZN -0.99%
TSLA -0.17%
UBER -1.41%
GS -6.93%
BAC -6.88%
JPM -0.82%
BRK.A +2.50%
COST -0.61%
XOM -1.05%
BABA -0.93%
WMT +1.92%
SPCX +3.39%
DIS +1.33%
F -2.81%
  • Discounts and special offers
  • Subscriber-only articles and interviews
  • Breaking news and trending topics

Already a subscriber?

By signing up, you accept Moneywise's Terms of Use, Subscription Agreement, and Privacy Policy.

Not interested ?

Debt
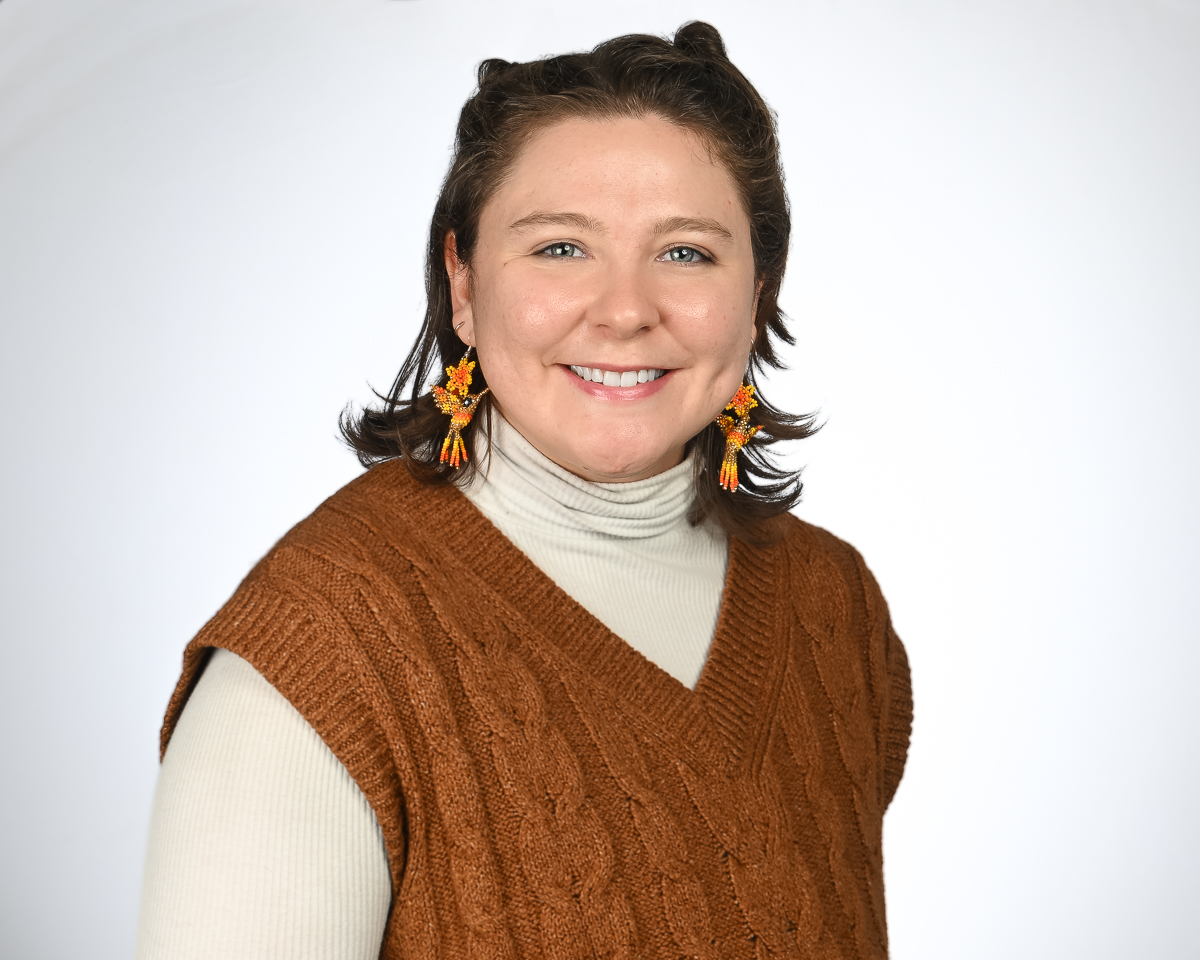
Photo of Erin Spencer in front of a sunset Erin Spencer

‘It felt like starting at rock bottom’: Woman filed for bankruptcy at 24 with $65,000 in debt. How she made it back from the brink

At age 24, when most people’s careers and financial journeys are just starting, Erin Spencer decided she needed to start over.

A combination of student and car loans, credit liabilities, a bad breakup and “living outside my means” left her $65,000 in debt, as she said in People. So when a trusted colleague suggested she file for bankruptcy, she went for it.

Advertisement

“I couldn’t afford the monthly payments toward my credit cards and line of credit, so when I filed, I was able to take a breath and almost start over,” Spencer told Moneywise.

Take control — get our free newsletter.

By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.

Spencer added that she still had to pay her student and car loans, but that the bankruptcy significantly lowered the cost to $180 a month for nine months. “It felt like starting at rock bottom again, rather than a reset,” she added, “but I don’t regret doing it.”

Now 31, Spencer is sharing her story on TikTok, demystifying bankruptcy and sharing advice to her younger self.

Spencer’s advice — and a warning that hitting reset comes at a price

Personal bankruptcy generally falls under Chapter 7, which forgives some debt and liquidates assets to pay the rest, or Chapter 13, which involves a repayment plan to avoid liquidation.

Last year, the number of personal bankruptcy petitions filed in U.S. courts jumped 11% from 2024 to 533,337. The most common causes of bankruptcy in the U.S. remain job losses and medical debt, while student loans and credit debt are also high on the list.

Excluding mortgage debt, the average U.S. debt balance hit $21,603 in 2025.

John Cooper, a certified financial planner with Greenwood Capital, told Moneywise that bankruptcy “is a viable solution” for those struggling with high levels of debt, “but not without first considering [or] exploring other options” like debt counseling, debt consolidation or making efforts “to settle the debt for less than the full amount” with the creditor.

Those who do pursue bankruptcy may have to meet certain criteria and take debt counseling to be eligible. And bankruptcy negatively impacts your credit score for up to seven to 10 years, with Cooper warning that it could make it “difficult to secure a credit card, loan, et cetera, in the foreseeable future.”

He added that “not all debts are automatically wiped away,” including some tax debts and even student loans.

Advertisement

Spencer, who is Canadian, spoke with an insolvency trustee, according to People, and decided that bankruptcy was the best option for her. In a TikTok video, she highlighted five pieces of advice she would tell her 24-year-old self about the experience, paraphrased below:

1. You’ll realize this is much more common than you think. You think you’re the only person in this much debt, unable to manage. You’re not.

2. It’s going to feel uncomfortable, but you need to get educated and face your finances head on! Come up with a plan and stick to it, even if you feel like you don’t have enough money.

3. Your financial ‘recovery’ journey is not going to be linear, especially if you don’t handle the habits.

4. Speaking honestly about your finances is going to change your life and that of others. Not only what you share on social media, but what you share with friends so they know you will sometimes have to say no to things. Your financial health is more important than going out to dinner.

Advertisement

5. I know you feel like this is the end of the road. This is just the beginning. You do recover and bounce back, it takes time, effort and persistence. You’re going to be OK.

Must Read

How to rebuild your finances and credit after bankruptcy

Rebuilding your finances and credit post-bankruptcy can take time. Spencer says that she now tracks “everything that I spend and almost pretend that my credit cards don’t exist.”

She added that in addition to being honest with people when she can’t afford to do something, she needed to increase her income “to avoid falling back into the same trap.”

That included finding a corporate job that paid more than what she’d previously made, as well as a content creation side hustle that landed her brand deals, affiliates and the opportunity to sell budget templates and spending trackers.

Advertisement

Experts also recommend that, post-bankruptcy, you meet with a financial planner or advisor to devise a realistic monthly budget.

Rebuilding your credit by paying bills on time is also key and, eventually, could mean taking on a secured credit card — where you put down a deposit that counts toward your borrowing limit — or become an authorized user on someone else’s card.

Others note that setting a timeline for your financial goals while also recognizing the importance of mentally and emotionally recovering from bankruptcy, can help with the transition forward.

Meanwhile, Spencer’s advice to young people dealing with mounting debt is to stop using credit, be honest with people in your life about your financial situation and don’t fall into the trap of trying to keep up with what you see on social media.

“Make a plan for your money and stick to it the best you can, track all your spending and your debt payoff journey so you can see you’re actually making progress,” she added. “Debt is really common, but it doesn’t mean you should justify it and use ‘You only live once’ as an excuse to overspend.”

You May Also Like

Share this:
Mike Crisolago Sr. Staff Reporter

Mike Crisolago is a Sr. Staff Reporter at Moneywise with nearly 20 years of experience working as a journalist, editor, content strategist and podcast host. He specializes in personal finance writing related to the 50-plus demographic and retirement, as well as politics and lifestyle content.

more from Mike Crisolago

Explore the latest

Disclaimer

The content provided on Moneywise is information to help users become financially literate. It is neither investment, tax nor legal advice, is not intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities, enter into any loan, mortgage or insurance agreements or to adopt any investment strategy. Tax, investment and all other decisions should be made, as appropriate, only with guidance from a qualified professional. We make no representation or warranty of any kind, either express or implied, with respect to the data provided, the timeliness thereof, the results to be obtained by the use thereof or any other matter. Advertisers are not responsible for the content of this site, including any editorials or reviews that may appear on this site. For complete and current information on any advertiser product, please visit their website.

†Terms and Conditions apply.