SPY -5.53%
BND +0.61%
QQQ -6.33%
DIA -4.12%
VNQ -2.75%
GLD -5.37%
BTC -6.66%
AAPL -2.15%
GOOGL -4.34%
NVDA -13.87%
MSFT -3.57%
META -7.77%
AMZN -6.25%
TSLA -8.51%
UBER -7.69%
GS -9.45%
BAC -3.39%
JPM -4.19%
BRK.A -0.98%
COST +0.50%
XOM -0.06%
BABA -3.01%
WMT +0.62%
SPCX -9.71%
DIS -3.58%
F -0.36%
  • Discounts and special offers
  • Subscriber-only articles and interviews
  • Breaking news and trending topics

Already a subscriber?

By signing up, you accept Moneywise's Terms of Use, Subscription Agreement, and Privacy Policy.

Not interested ?

Mortgages
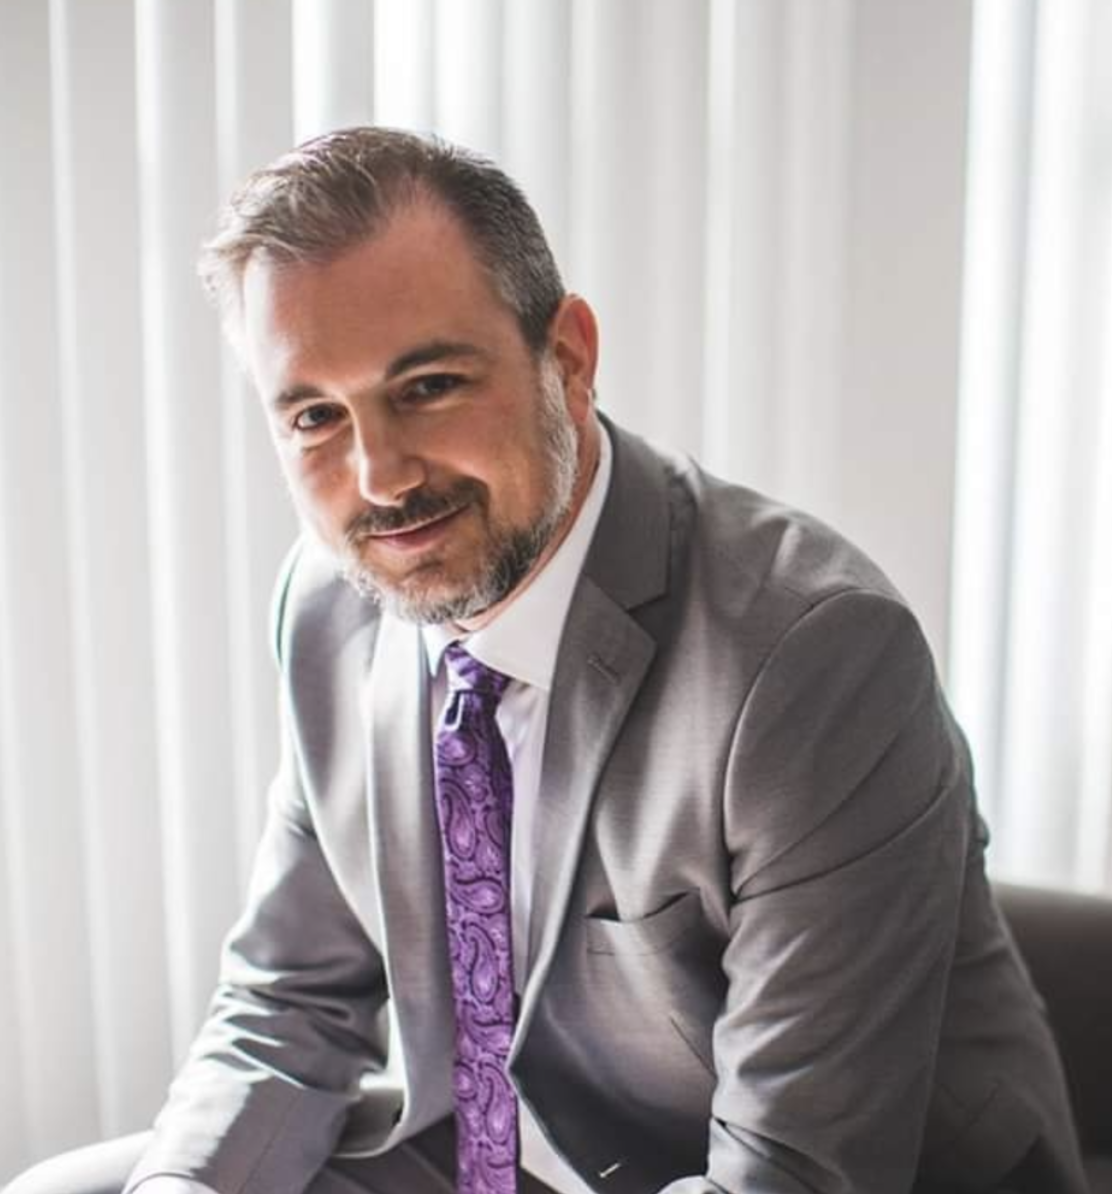
An image of financial expert Ramit Sethi from 2011. Jemal Countess/Getty Images

Ramit Sethi says paying off your mortgage early is short-sighted — the math behind his case for investing instead

Paying off your mortgage early might sound like the ultimate financial milestone. After all, eliminating what is likely your largest monthly bill can offer you better financial security and peace of mind.

But personal finance expert Ramit Sethi argues that rushing to become mortgage-free could actually cost homeowners a significant amount of money in the long run.

Advertisement

In an Oct. 11 post on X, the author of “I Will Teach You to Be Rich” called paying off a house too quickly one of the most short-sighted financial decisions people can make.

Stay ahead of the mortgage market, free.

By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.

“Rushing to pay off a house — now what?” Sethi wrote, pointing out that homeowners still face ongoing expenses even after eliminating their mortgage, while potentially sacrificing decades of investment gains along the way.

His argument comes at a time when Americans are carrying record levels of household debt and facing substantial housing costs. According to the Federal Reserve Bank of New York, total U.S. household debt reached $19.1 trillion in the third quarter of 2026, including $13.4 trillion in mortgage balances.

So should homeowners prioritize eliminating their mortgage or put that extra money toward building wealth through investments?

Sethi says paying off your mortgage early can be a mistake

Sethi’s argument largely comes down to opportunity cost: Money used to make additional mortgage payments is money that could potentially generate returns elsewhere.

For example, someone with a relatively low fixed mortgage rate might be better off making their required monthly payments and investing the additional cash in a diversified portfolio. Over several decades, investment returns could potentially outpace the interest they’re paying on their home.

Consider someone with an extra $500 per month. Putting that money toward the mortgage principal would reduce the outstanding balance and save interest over the life of the loan. But investing that same $500 monthly in the stock market could generate substantial returns through compounded growth.

At an illustrative 7% annual return, investing $500 monthly for 30 years could grow to approximately $610,000. Actual market returns aren’t guaranteed, however, and investments can lose value.

Advertisement

It’s also worth noting, however, that homeowners don’t eliminate all their housing expenses by paying off their mortgages. Property taxes, homeowners insurance, maintenance and unexpected repairs remain your responsibility as long as you own the home.

Must Read

With housing costs rising, should Americans invest instead?

The decision of investing versus paying down a home loan is particularly relevant in 2026, given how expensive homeownership has become.

According to Freddie Mac’s Nov. 19 mortgage rate survey, the average 30-year fixed mortgage rate reached 7.28%, up from 6.26% a year earlier. The average 15-year fixed rate was 6.66%.

Meanwhile, the National Association of Realtors reported that the median existing-home price reached $416,700 in October, marking the 40th consecutive month of year-over-year price increases.

The broader household debt picture is also concerning. The New York Fed reported that Americans owed $1.29 trillion in credit card debt and $1.73 trillion in auto loans in the third quarter. Overall, 5% of outstanding household debt was in some stage of delinquency.

Advertisement

That doesn’t necessarily mean homeowners should abandon the goal of paying down their mortgages. Rather, Sethi’s argument highlights the importance of considering what else your money could accomplish.

Generally, homeowners with low fixed mortgage rates, sufficient emergency savings and no high-interest debt may benefit from prioritizing investments over additional mortgage payments. Someone paying 7% interest on a mortgage, however, faces a very different calculation than someone who locked in a rate below 3% several years ago.

Ultimately, paying off a mortgage early offers a guaranteed interest savings and the psychological benefit of eliminating debt. Investing offers the potential for greater long-term returns, but comes with market risk.

The best strategy depends on the mortgage rate, investment timeline, tax situation and personal tolerance for debt. As Sethi’s argument suggests, being debt-free and building the greatest possible net worth aren’t necessarily the same financial goal.

You May Also Like

Share this:
AnnaMarie Houlis Weekend Editor

AnnaMarie Houlis is a journalist and author with more than 15 years of experience, thousands of bylines and four books covering everything from travel, lifestyle and wellness to finance, technology and business.

more from AnnaMarie Houlis

Explore the latest

Disclaimer

The content provided on Moneywise is information to help users become financially literate. It is neither investment, tax nor legal advice, is not intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities, enter into any loan, mortgage or insurance agreements or to adopt any investment strategy. Tax, investment and all other decisions should be made, as appropriate, only with guidance from a qualified professional. We make no representation or warranty of any kind, either express or implied, with respect to the data provided, the timeliness thereof, the results to be obtained by the use thereof or any other matter. Advertisers are not responsible for the content of this site, including any editorials or reviews that may appear on this site. For complete and current information on any advertiser product, please visit their website.

†Terms and Conditions apply.