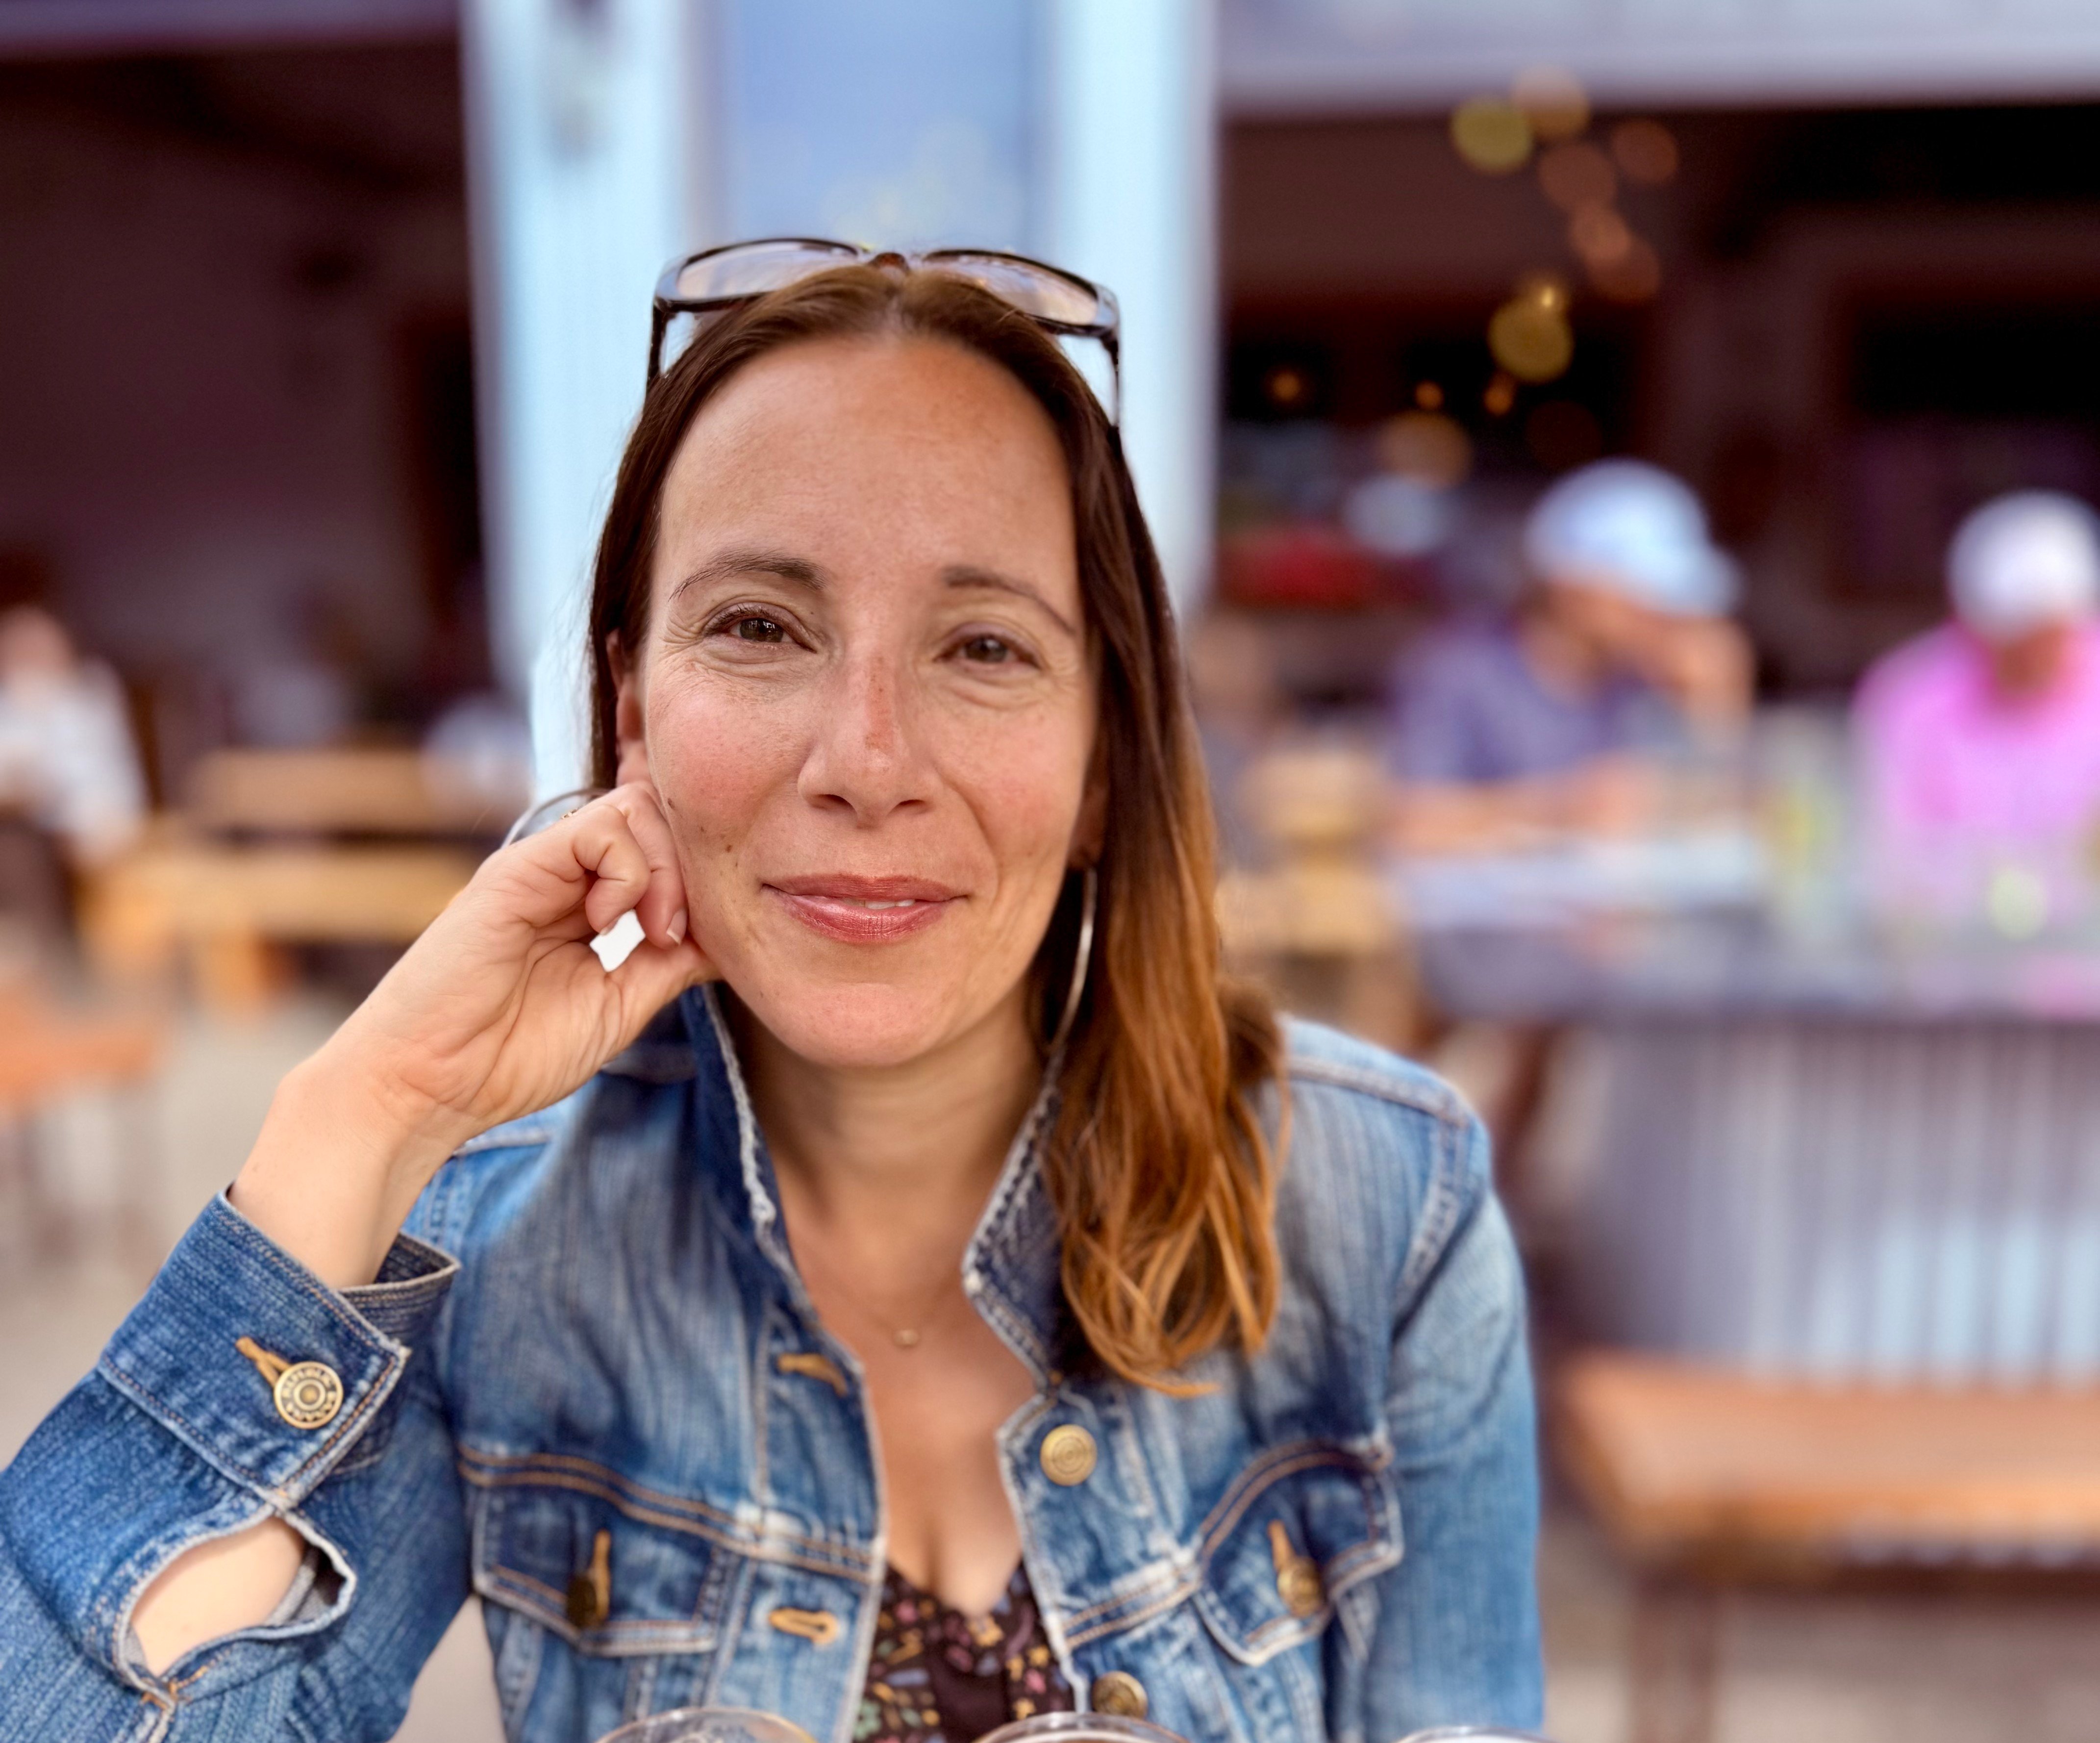
Taryn Williams didn’t grow up in a household that talked about money — not in the investing sense, anyway. The people around her lived paycheck to paycheck, and retiring well was something that happened to other people.
But “One of the first things I learned is that time is money when it comes to investing,” she writes in Business Insider. “I knew that with as little money as I had at the time, compound interest could only work once I started the process.”
So, she taught herself, starting in high school, working her way through personal finance blogs and retirement calculators before starting her career.
Thanks for subscribing!
Retire on your terms — we'll show you how.
By signing up, you accept Moneywise Terms of Use, Subscription Agreement, and Privacy Policy.
Ten years later, that self-education has paid off, she notes. At 34, Williams crossed a threshold where, mathematically speaking, she may not need to save another dollar for retirement.
That’s the power of what’s known as Coast FIRE, a concept that more people should be running the numbers on.
What Coast FIRE means
Coast FIRE is a variation on the broader FIRE (Financial Independence, Retire Early) movement — but with a crucial difference in approach. Rather than racing to save aggressively enough to retire early, the goal is to invest enough at a young age that compound growth alone can carry the portfolio to a sufficient retirement balance.
The math works because of compounding. Compound interest means you earn returns not just on your principal, but on all the interest your investment has already accumulated. The earlier you start and the longer you stay invested, the more dramatic the effect.
As Investor.gov notes, some experts consider a 7% to 10% annual return a helpful long-term estimate for diversified U.S. stock investments based on historical averages.
The earlier you start, the less you need to save: time does the heavy lifting. Once you’ve reached your Coast FIRE number, you only need to earn enough to cover day-to-day expenses, as your retirement math is effectively done.
Williams’ calculation is simple: $140,000 invested at 34, growing at 7.5% annually for 33 years, reaches approximately $1.5 million by 67.
Must Read
- Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
- The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
How she got there on a teacher’s salary
Williams says she never made a high salary — she’s spent her career earning what she describes as a “modest teacher salary or less.” But what she did have was consistency and a pay-yourself-first approach.
After graduating from college, she opened both a 403(b) through her employer and a Roth IRA that she managed independently. Her system was to first figure out how much she needed to max out her Roth IRA, then allocate the rest. She contributed something every month, even when amounts were small.
Williams also made a deliberate choice not to sacrifice her present life entirely for her future one. She traveled. She attended concerts. She spent on things she valued, and has no regrets. “I knew I didn’t want to be one of those people who waited until retirement for their lives to start,” she writes.
The number most people aren’t calculating
Many retirement conversations focus on contribution rates, account balances and what you’re saving each year. But the Coast FIRE framework flips the question: how much do you need invested right now, at your current age, for compound growth alone to carry you to retirement?
The answer varies significantly by age. A 25-year-old needs far less invested than a 40-year-old to reach the same retirement target, because they have more time for compounding to work. The earlier the starting point, the lower the Coast FIRE threshold.
“Knowing I can retire one day gives me a sense of financial peace,” Williams writes. “This is significant, as it’s not something that I’ve ever experienced.”
Run the math yourself
For anyone who grew up without financial role models, like Williams, the Department of Labor’s retirement planning guidance offers a starting point: the combination of consistent saving and compound growth is how ordinary earners close the retirement gap over time.
The key variables are your current balance, your assumed rate of return and your time horizon — all of which you can test using Investor.gov’s compound interest calculator.
Williams’ approach applies to anyone at any income level: decide on a retirement goal, run the numbers and find out how much time and compounding can do on your behalf before you need to do the rest yourself.
You May Also Like
- Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake — here’s what it is and 3 simple steps to fix it ASAP
- A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
With a writing and editing career spanning over 15 years, Emma creates and refines content across a broad spectrum of industries, including personal finance, lifestyle, travel, health & wellness, real estate, beauty & fitness and B2B/SaaS/tech.